Every January, millions of retirees eagerly anticipate a bump in their Social Security checks, only to find the actual increase falls unexpectedly short. The culprit is your Medicare Part B premium, which routinely outpaces the annual Cost-of-Living Adjustment and quietly consumes a large chunk of your monthly raise. For 2026, the standard Part B premium jumped to $202.90—swallowing roughly a third of the average retiree’s cost-of-living bump before it reaches the bank. Understanding this recurring financial squeeze is essential because monetary strain directly influences your physical and mental well-being. By maximizing the hidden value in your Medicare benefits, you can protect your health and wallet from these annual deductions.
The Science Snapshot: How Financial Strain Impacts Biological Health
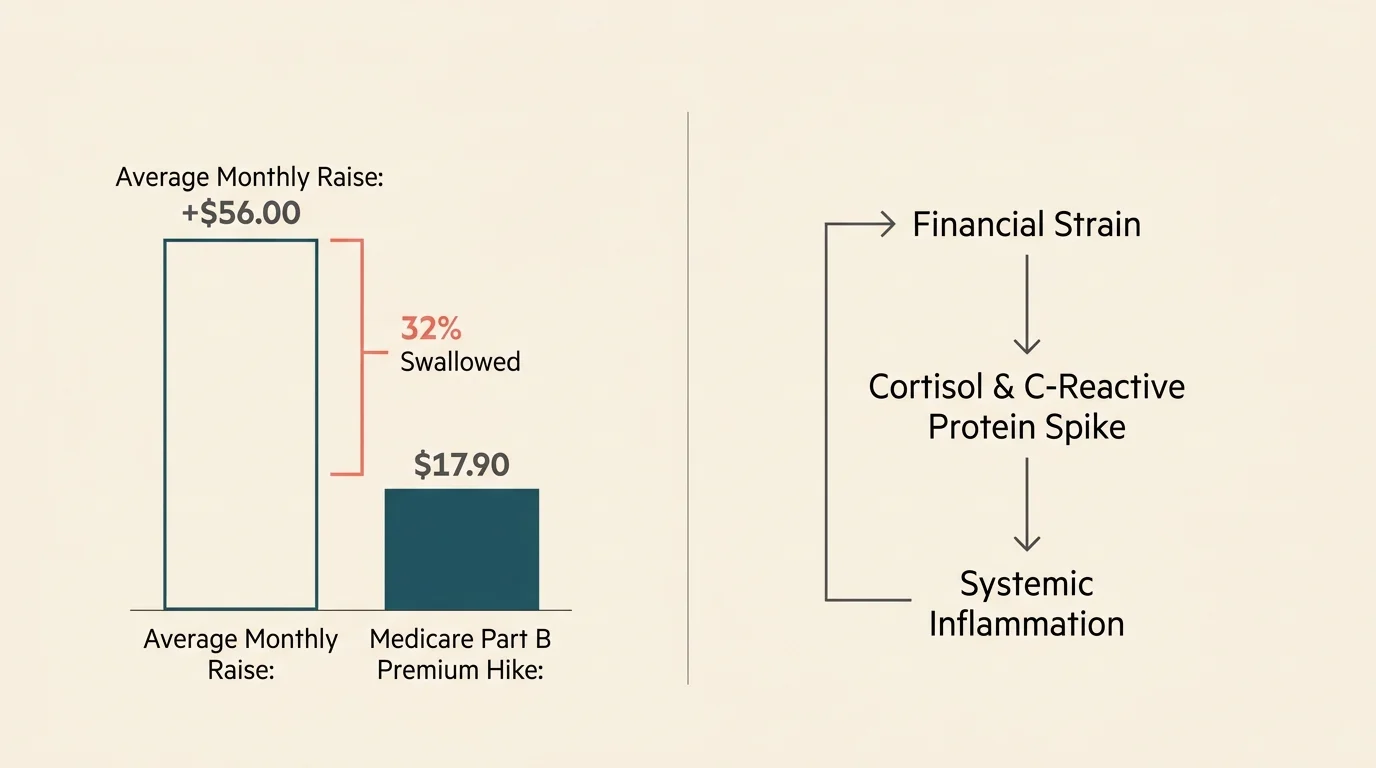
To fully grasp the magnitude of this issue, it helps to examine the raw numbers. In 2026, the Social Security Cost-of-Living Adjustment was set at 2.8 percent, increasing the average beneficiary’s check by approximately $56 per month. Meanwhile, the standard Medicare Part B premium jumped from $185.00 to $202.90. That $17.90 hike instantly consumes about 32 percent of the average raise. For retirees collecting smaller checks, this premium increase devours an even larger percentage. While a protective federal provision ensures your net check amount does not decrease year-over-year, it effectively means your overall raise can be severely stunted.
This dynamic represents much more than a budgeting frustration; it is a profound medical issue. Research published in Brain, Behavior, and Immunity highlights that chronic financial stress operates as a persistent, destructive threat to your nervous and immune systems. When you worry about affording basic household necessities or copays, your body triggers a perpetual fight-or-flight response. This reaction floods your system with cortisol and inflammatory markers, such as C-reactive protein. Over an extended period, this heightened biological risk translates into accelerated physical deterioration. Financial toxicity significantly increases the likelihood of developing cardiovascular disease, chronic anxiety, clinical depression, and high-impact physical pain. Protecting your long-term health requires actively offsetting this strain.
Strategy Pillars: Reclaiming Your Health and Your Wealth
You cannot change the federally mandated premium rates, but you can change how you utilize your healthcare coverage. By focusing on preventive care, smart nutrition, consistent movement, and mindset shifts, you mitigate the sting of rising medical costs.
Pillar One: Maximize Your Medical Care Value
Since the federal government automatically deducts that $202.90 from your check every month, you should aggressively utilize the services it covers. Many people view Part B strictly as reactive sick care. In reality, it includes a robust suite of preventive services that do not cost a penny out of pocket when you see a participating doctor. The Annual Wellness Visit stands as the cornerstone of this benefit. It is a personalized prevention planning session where your physician assesses your cognitive function, thoroughly reviews your prescription medications, and maps out a schedule for necessary life-saving screenings.
By taking advantage of free screenings for cardiovascular disease, osteoporosis, and certain cancers, you catch potential issues before they require invasive interventions. The official Medicare website outlines dozens of covered tests. For example, abdominal aortic aneurysm ultrasounds and depression screenings are fully covered under Part B. Medicare also covers up to two diabetes screenings per year for individuals at high risk. Catching a chronic condition early dramatically lowers future out-of-pocket medical costs. Always explicitly verify with your doctor’s billing office that you are scheduling a free preventive visit to avoid surprise diagnostic fees.
Pillar Two: Leverage Preventive Nutrition Therapy
Eating a health-promoting diet often feels expensive, yet it remains your best defense against costly medical interventions. Medicare Part B covers Medical Nutrition Therapy services if you have diabetes, kidney disease, or a recent kidney transplant. This valuable service provides three hours of initial counseling with a registered dietitian in your first year. A clinical professional teaches you how to stabilize blood sugar and improve kidney function using affordable pantry staples without paying any deductibles.
Even if you do not qualify for targeted therapy, optimize your diet to stretch your budget. Prioritize seasonal produce, which consistently costs less and offers higher nutrient density. Rely heavily on plant-based proteins such as brown lentils, chickpeas, and black beans several times a week. These highly affordable foods are rich in soluble fiber, which supports healthy blood pressure and pulls excess cholesterol out of your bloodstream. Utilizing food as medicine effectively lowers your risk of needing expensive pharmaceutical interventions down the road.
Pillar Three: Movement as Free Preventative Medicine
Consistent exercise is a potent, zero-cost intervention for physical and financial health. The Centers for Disease Control and Prevention emphasizes that regular physical activity reduces the risk of chronic conditions that drive up healthcare costs, such as heart disease and type 2 diabetes. When you prioritize staying active, you improve your balance and bone density. This directly reduces your risk of devastating falls, which are a leading cause of massive hospital bills for older adults. From a biological standpoint, the endorphin release generated by exercise also serves as a direct antidote to the stress hormones triggered by financial anxiety.
You do not need a pricey gym membership to reap these profound physiological benefits. Walking remains one of the most effective cardiovascular exercises available. Aim for a brisk, daily walk around your neighborhood or local park. Incorporate simple bodyweight exercises like wall push-ups, chair squats, and calf raises into your morning routine to build essential functional strength. If you have a Medicare Advantage plan, you might even have access to free fitness programs like SilverSneakers. For those remaining on standard Part B, local community centers frequently host low-cost movement classes tailored specifically to older adults.
Pillar Four: Shift Your Mindset and Reduce Financial Stress
Unmanaged financial stress creates a vicious cycle where chronic anxiety leads to poor sleep, elevated blood pressure, and weakened systemic immunity. Breaking this self-perpetuating cycle requires a deliberate mindset shift. Instead of feeling helpless against rising Part B premiums, focus entirely on the variables you can actively control. Practice daily stress-reduction techniques such as deep diaphragmatic breathing or guided meditation. The National Institute on Aging notes that managing chronic stress is vital for healthy aging. These simple, free techniques have been clinically shown to lower circulating cortisol levels and mitigate the severe biological damage caused by chronic worry.
Furthermore, recognize that tangible help is available. If the $202.90 premium creates a genuine financial hardship, you may qualify for a Medicare Savings Program. These vital state-administered programs help pay for Part B premiums, and depending on your income, they may also cover deductibles. Contact your local State Health Insurance Assistance Program to receive completely free, unbiased counseling regarding your eligibility for these benefits. Reframing your situation from one of passive loss to active resource management fundamentally empowers you. This proactive approach directly improves your mental health.
Real Voices: Perspectives from the Frontline
Conversations with primary care physicians and geriatric financial navigators reveal a stark reality. Many older adults quietly skip their prescribed medications or delay necessary diagnostic appointments when they see their Social Security checks stagnating against rising costs. Health professionals continually emphasize that avoiding preventative care to save a few dollars usually results in catastrophic health events that cost exponentially more in the long run.
Clinical dietitians frequently note that their patients are incredibly surprised to learn that complex nutrition counseling is fully covered under Part B for specific chronic conditions. One universal sentiment among patient health advocates is that relentless persistence pays off. Patients who actively ask their doctors about free preventive screenings often end up receiving thousands of dollars in vital care over a few years. The overarching advice from geriatric care specialists is to view your primary care provider as a dedicated partner in both your physical and financial health. Be totally transparent with them if you are struggling with out-of-pocket costs so they can switch you to generic medications or seamlessly adjust your care plan.
Frequently Asked Questions
Navigating the complex intersection of Social Security benefits and Medicare regulations is challenging. Here are evidence-based answers to some of the most common questions about how your premiums and raises interact.
Why does the Part B premium increase so much faster than general inflation?
The Cost-of-Living Adjustment is based on standard consumer inflation, tracking everyday goods like gasoline, groceries, and clothing. However, the Medicare Part B premium is intrinsically tied to healthcare inflation, which consistently rises at a faster rate than consumer goods. The costs of physician-administered drugs and advanced outpatient treatments drive these specific premiums up sharply. Consequently, your Social Security raise simply struggles to keep pace with the hyper-inflated medical sector.
Can a Medicare premium increase actually make my Social Security check go down?
For the vast majority of beneficiaries, the answer is no. A federal provision known as the hold harmless rule legally protects your benefits. This rule states that your standard Part B premium increase cannot exceed the dollar amount of your Cost-of-Living Adjustment. For instance, if your COLA equates to $15, your specific premium will only rise by $15. However, this vital protection does not apply to new Medicare enrollees or higher-income earners.
Are Medicare Advantage plans a better financial choice to avoid these costs?
Medicare Advantage plans sometimes advertise zero-dollar additional premiums and include perks like basic dental benefits. However, you are still legally required to pay your baseline Medicare Part B premium, meaning these plans do not eliminate the automatic deduction from your Social Security check. Furthermore, Advantage plans often restrict your choice of doctors through tight provider networks and require pre-authorization for necessary treatments. You should carefully evaluate your specific health needs with an independent insurance counselor before making any permanent switch.
How do I know which preventive services are entirely free?
The Centers for Medicare and Medicaid Services strictly defines which services carry zero out-of-pocket costs. These generally include your Annual Wellness Visit, specific preventative vaccinations, and targeted disease screenings based on your age. However, if your doctor discovers a new medical issue during a free screening and investigates it further during the exact same visit, the appointment may be reclassified as a diagnostic visit. This immediately triggers a standard copay and deductible.
Your Next Empowering Step
It is understandably frustrating to watch a hard-earned financial raise vanish before you even get the opportunity to spend it. Yet, allowing persistent financial anxiety to fester will only compromise your biological health and drive up your future medical costs. You possess the inherent power to reclaim the true value of those deducted dollars by actively engaging with your Medicare benefits and prioritizing high-impact, low-cost lifestyle interventions.
Your most manageable first step is to call your primary care provider and schedule your Annual Wellness Visit if you have not done so this year. Take a dedicated notebook with you and ask your physician exactly which free preventive screenings you are eligible to receive based on your unique health history. Next, consider what small, zero-cost physical habit you can start today. Perhaps you can commit to a ten-minute walk after dinner or swap an expensive processed snack for a handful of highly affordable, fiber-rich legumes. Take immediate control of your preventative care today, and fiercely ensure your money serves your long-term vitality.
Leave a Reply